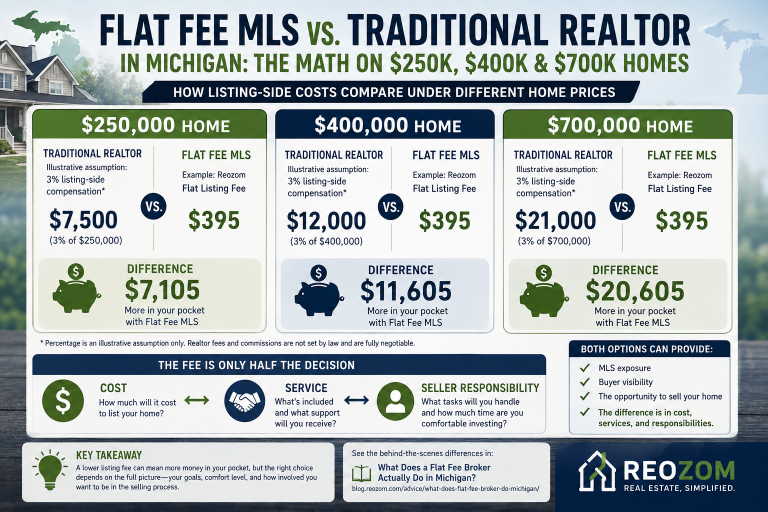
A $400,000 sale doesn't mean $400,000 reaches your bank...
No posts found
Michigan Flat Fee MLS: How to Compare Appraisal Gap Offers
Two buyers offer to purchase your Michigan home. The higher offer includes a $10,000 appraisal-gap clause. The other buyer offers less and promises a smaller gap. Which offer leaves you with more room if the appraisal comes in low? That depends on the language in each offer, the appraisal result and the cash the buyer can actually bring to closing. Run the same three appraisal scenarios for both buyers before choosing.
What an appraisal gap means for a seller
An appraisal gap is the difference between the contract price and a lower appraised value. A $350,000 contract and a $335,000 appraisal create a $15,000 gap. The buyer and lender still have to work through the loan and cash requirements, and the signed agreement controls the parties’ deadlines and options. The CFPB’s guide to a low appraisal explains why a buyer might ask to renegotiate.
Read the gap clause alongside the appraisal and financing contingencies. Ask your broker or real estate attorney how the papers work together, especially what happens if the appraisal falls below the amount the buyer has agreed to cover. If you are choosing a listing package, check who can help review incoming terms through Reozom’s Michigan flat fee MLS service. The Michigan flat fee broker guide explains how to compare responsibilities.
Build a three-number worksheet
Create one column per offer. Copy in the purchase price, maximum gap amount, seller credits, appraisal deadline, required notice and financing deadline. Note any minimum appraised value and how the contract handles an appraisal below that level. Record what the buyer has supplied about funds available for closing and ask what still needs confirmation.
Choose three hypothetical appraisal values and use them across every offer. Start with a value that supports both prices, a value where only one buyer’s cap covers the gap, and a lower value that exceeds both caps. These are stress tests. Your broker can help you select values informed by recent comparable sales, but the lender’s appraisal can differ.
For each value, subtract the appraisal from the offer price. Record zero if the result is negative. Then subtract the buyer’s gap cap from any positive gap, again recording zero for a negative result. The remainder is the amount above the cap in this exercise. Write down what the document says happens next, who must give written notice, and when. Ask about ambiguous language before relying on the calculation.
$350,000 contract price
$335,000 appraised value
$15,000 difference in this hypothetical comparison.
A hypothetical Grand Rapids sale
Offer A is $350,000 with a $10,000 gap cap and a $4,000 seller credit. Offer B is $345,000 with a $7,500 cap and no credit. Assume both offers are financed, each cap means the buyer has agreed to cover up to that amount, and neither agreement sets a separate minimum appraisal value. Actual offers may work differently.
At $350,000, both gap amounts are zero. Subtracting just the credit gives A a price less credit of $346,000, compared with B at $345,000. Those figures exclude all other seller costs. At $339,000, A has an $11,000 gap and exceeds its cap by $1,000. B has a $6,000 gap, which is within its cap. For A, check what the agreement says about a shortfall above the cap. For B, confirm what the buyer and lender still need to close.
At $335,000, A has a $15,000 gap, which exceeds its cap by $5,000. B has a $10,000 gap and exceeds its cap by $2,500. Suppose A and B each asked the seller to reduce the price by the amount over their respective caps, and the parties agreed. With credits unchanged, A would be $341,000 before other costs, and B would be $342,500. That hypothetical result favors B by $1,500, even though A offered $5,000 more at signing.
Compare the rest of the offer before signing
The worksheet helps you see what drives the outcome. It cannot tell you whether either buyer will close. Put the closing and possession dates beside the appraisal deadline, confirm the source of any proposed seller credit, and list remaining inspection or financing conditions. When an offer already includes a repair request, run that alongside the credit using Reozom’s guide to comparing Michigan offers when repairs are on the table.
Before promising a move-out date, compare two timelines: one where the deal closes as planned and one where a low appraisal triggers a new round of negotiations. Record the next date you would have to pay for storage, movers or another month of housing, and flag it beside the offer deadline. If you are still waiting for the first written proposal, the Reozom showing-to-offer worksheet helps you diagnose what is happening earlier in the process.
If the appraisal has already arrived, put the notice deadline on the calendar and ask which agreement provision applies to the request you received. If your records suggest a material factual error, gather evidence such as a permitted addition or recent comparable sale and ask the buyer side about the lender’s process. The federal interagency guidance on reconsideration of value describes how financial institutions can review concerns about valuations. Keep tracking the agreed deadlines while a review is pending.
Frequently asked questions
Does a bigger gap cap always mean a stronger offer?
Compare the cap to the offered price and likely scenarios. A high-priced offer can exceed its larger cap before a lower-priced offer exceeds its smaller one. Compare credits, closing dates and remaining conditions at the same time.
Can the buyer use earnest money to cover the gap?
Ask the lender and closing agent how the deposit is credited and how much cash the buyer still needs. Counting a deposit as additional cash when it is already part of the closing calculation can double-count the same money.
What if the appraisal comes in above the purchase price?
There is no low-value gap in that scenario. The purchase agreement still controls the sale price and the transaction can have other open conditions, such as underwriting approval or an inspection deadline.
Does the seller automatically have to reduce the price?
Review the signed agreement before assuming either side must change the price. Confirm which notices, options and deadlines apply and document any agreed change in writing with the appropriate professional.
What can a seller share to support a review?
Identify the specific fact you think is incorrect and supply a source where available. Send the information through the channel the lender identifies. Keep a dated record of what was shared and when you expect the next update.
What should I ask before accepting an offer with a gap clause?
Ask what happens when the appraisal is one dollar below the clause’s stated limit, who has to give notice, and when the lender can confirm the buyer’s revised cash requirements. Get the answers before scheduling around the closing date.